How to Negotiate Repairs Before Closing on a Home
Learn how to negotiate repairs before closing, prioritize issues, request credits or repairs, and handle seller responses effectively.
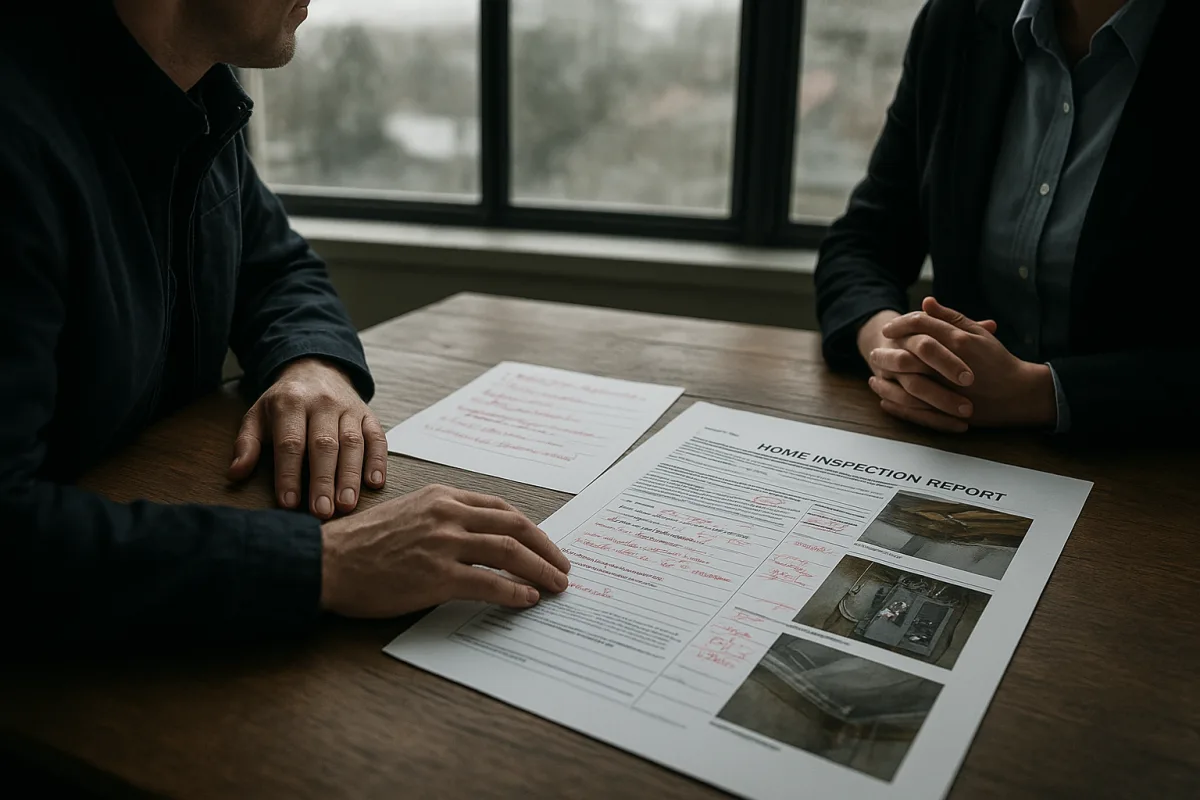
Read the inspection report line by line
The inspection report may show a leaking water heater in the utility room, missing roof shingles, an aging electrical panel, and a loose bathroom handrail. Start by marking each item’s exact location, the inspector’s description, stated consequence, and supporting photograph.
A good report gives you a foundation for a focused request. It should identify what was observed, where it was found, what it could affect, and include photos that let the seller understand the issue without guessing. [15][16]
Do not turn the report into a shopping list. An inspection report identifies conditions observed on inspection day, but it does not automatically require a seller to repair every defect listed. [15][17]
We would separate findings into three groups: urgent safety or structural concerns, essential systems that may fail or require major expense, and routine maintenance or cosmetic work. The first two groups belong at the center of your negotiation. [11]
Safety issues can include electrical hazards, water intrusion, or conditions that affect the home’s habitability. Structural concerns, roof defects, plumbing failures, and broken heating or cooling systems can also carry costs far beyond a loose cabinet pull or worn paint. [11][14]
Put the likely repair cost beside each major finding
A contractor’s estimate can sharpen a request, but even broad cost ranges help you see which inspection items could materially change your closing budget. Use the figures as a starting point, not as a guaranteed local quote.
Minor roof repairs commonly run from $350 to $1,500, while a full roof replacement can cost $9,000 to $25,000 or more. [6] A report that says “damaged shingles” and a report that identifies widespread deterioration can therefore lead to very different requests.
Minor HVAC repairs may cost $300 to $2,000, while replacing a heating and cooling system can run $6,000 to $13,000. [7] If the inspector flags an aging system but cannot determine its remaining life, ask for clarity before treating replacement as an immediate cost.
Minor plumbing repairs are estimated at $150 to $500, but major plumbing work can reach $5,000 to $15,000. [6] Water heater replacement falls in a separate range of about $1,300 to $2,600, and an electrical panel upgrade may cost $1,800 to $4,000. [6]
These ranges explain why a short, well-supported request often carries more weight than a long list of small defects. A seller may engage with a documented active leak or unsafe panel, while resisting a request that also includes caulk, touch-up paint, and minor wear.
Check your contract clock before asking for anything
Your inspection contingency and purchase contract set the deadlines that control this process. Typical inspection periods run seven to 15 days after the offer is accepted, and repair requests are often due within seven to 15 days of contract execution. [5]
Sellers commonly receive three to 10 days to respond, with the agreement completed before closing. [5] Those ranges are not a national rule, however, because deadlines vary by contract terms and local practice.
Read the actual contingency language with your agent as soon as the inspection arrives. Missing a request deadline can reduce your leverage or affect your contractual options, even if the defect itself is significant.
There is no established nationwide figure for how long repairs take after an agreement is signed. Do not promise yourself that a repair will be finished by a certain date unless the written agreement gives a completion date and spells out what happens if work is delayed.
Choose the form of your request
You generally have three paths: ask the seller to complete specific repairs, seek a credit toward your closing costs, or negotiate a price reduction. [1][5] Each changes who manages the work, when money changes hands, and whether your mortgage program allows it.
Seller repairs keep the work on the seller’s side before closing. This can fit a problem that must be corrected to meet loan requirements, or an issue you do not want to inherit without seeing the completed result.
A repair credit reduces the seller’s proceeds and is generally applied to your eligible closing costs. It cannot exceed your closing costs or the contribution limits set by your loan program, so a large repair estimate does not necessarily mean you can receive an equally large credit. [10]
A price reduction lowers the purchase price, but it does not put repair money in your pocket at closing. If you need cash to pay a contractor soon after you take ownership, compare that result with a permitted closing-cost credit.
Sellers may favor credits because they avoid arranging contractors, supervising work, and handling repair delays. [9] They may also resist them because the credit visibly reduces their net proceeds. [9]
We would request seller completion for a clearly defined issue that your lender requires repaired before closing. For an issue you want addressed by a contractor you select after closing, a credit may be cleaner if your closing-cost total and loan cap leave room for it.
Check FHA and VA rules before proposing a credit
A credit cannot replace repairs that FHA or VA financing requires before closing. In that situation, the seller must complete the required work, even if both sides would prefer to settle with a credit. [8]
Tell your lender about the inspection issues before you finalize your response. The lender can identify whether the appraisal, property standards, or loan program creates a condition that must be resolved before funds are released.
This is also where the difference between a repair preference and a loan condition becomes important. A seller can refuse a request for an old appliance or cosmetic update, but a loan-related repair requirement may prevent the transaction from closing until it is resolved.
Loan rules, title customs, escrow arrangements, and disclosure requirements can differ by state. California commonly splits escrow costs and has the seller pay title insurance, Texas commonly has the seller pay the owner’s title policy and the buyer pay the lender’s policy, while New York commonly places transfer taxes on the seller and title insurance on the buyer. [5]
Those closing-cost allocations can affect how much usable room exists for a credit. Ask your lender and local closing professional to show how a proposed credit would appear on your Closing Disclosure and whether your program permits the amount.
Write a request the seller can answer
Put the request in writing through the process your contract requires. State the inspection item, its location, the reported condition, the remedy requested, and whether you want licensed work, receipts, paid invoices, or a credit. [1][16]
For example, avoid “fix plumbing.” A clearer request identifies the leak’s location, refers to the report and photo, and asks for correction by a qualified professional before closing, with documentation available before the final walk-through.
Keep the request proportionate to the findings and the deal. Overloading it with small maintenance items can distract from serious defects and make the seller less willing to negotiate the issues that affect safety, financing, or a major system. [11][13]
A seller’s financial constraints may shape the response. [12] The seller may agree to a smaller credit, offer to repair one item but not another, or decline entirely, so rank your requests before you send them.
Do not rely on spoken assurances from a listing agent, seller, contractor, or anyone else. The agreed repair, credit, price adjustment, timing, and documentation need to appear in a signed contract amendment or addendum. [1][5]
Compare the seller’s response against your actual exposure
When the response arrives, compare it to the report and estimated scope, not merely to the seller’s wording. “Repair roof” could mean replacing a few shingles, sealing a flashing point, or addressing a broader problem.
If the seller offers a repair, clarify what work will be done and who will do it. If the seller offers a credit, check the dollar amount against your allowed closing costs, your loan’s limits, and the work you expect to arrange after closing. [10]
A $2,000 credit might cover a minor HVAC repair at the reported $300-to-$2,000 range. [7] It would be far short of a $6,000-to-$13,000 HVAC replacement, so treating the two outcomes as interchangeable could leave you with a substantial post-closing bill. [7]
Likewise, a price reduction may help your long-term financing amount but may not solve an immediate $1,300-to-$2,600 water-heater replacement. [6] Match the settlement structure to the timing and size of the expense you expect to face.
The seller remains free to refuse requests unless a contract obligation or legal requirement applies. [17] If that happens, review the inspection contingency, deadlines, and any options in your signed agreement with your agent and appropriate licensed professionals.
Put the agreement into the contract
A repair agreement should identify the exact items, the responsible party, the required completion date, and any proof you will receive. If the seller is giving a credit, the addendum should state the amount and the permitted closing-cost treatment.
Ask for enough detail that you can evaluate the repair at the walk-through. A vague promise to “address electrical issues” gives you little way to determine whether the seller corrected the condition the inspector found.
If contractors will perform work, documentation can include invoices, receipts, warranties, or other records specified in the agreement. The agreement can also state whether repairs must be completed by qualified or licensed professionals where that is appropriate.
Do not assume the seller’s repair obligation includes unrelated conditions discovered later. If a second inspection or contractor visit reveals a different issue, check your contract timing before adding it to the negotiation.
Inspect the repairs at the final walk-through
Bring the signed repair addendum, inspection report, photos, and any promised invoices to the final walk-through. Go directly to each agreed repair and compare the visible result with the written commitment.
Test what can be tested during a walk-through without damaging anything. Look for active leaks, operate the relevant fixtures or systems where appropriate, and check that documentation matches the home and the work described.
The final walk-through is the point to identify incomplete work, missing proof, or a repair that does not appear to address the agreed condition. [5] Raise concerns before closing, while the seller’s contractual responsibility and the closing process are still in front of you.
Do not let a clean-looking patch substitute for verification where the issue was safety-related, structural, or tied to financing. If the agreement required a particular repair or documentation, compare what you receive against that language before you sign closing papers.
Frequently Asked Questions
How do I prioritize repairs to negotiate before closing?
Focus first on urgent safety or structural concerns, such as electrical hazards, water intrusion, or roof defects. Next, address essential systems that may fail or require major expense, like heating and cooling or plumbing issues. Cosmetic and routine maintenance items should generally be left off the initial request.
What are the best ways to request repairs after a home inspection?
Make every request in writing, clearly tied to the inspection report’s location, description, photos, and the repair outcome you want. Use the inspection report to support your requests and avoid turning it into a long list of minor defects. Including estimated repair costs can also help clarify the significance of each issue.
Should I ask for repairs, credits, or price reductions before closing?
Choose between seller repairs, closing-cost credits, or price reductions based on your loan rules, available closing costs, and your ability to manage repairs after closing. Some loans require mandatory repairs before closing and do not allow credits to substitute for those repairs. Consider what works best for your situation and financing.
How do I handle a seller who refuses to make requested repairs?
Sellers are not legally obligated to make repairs unless the contract, an addendum, or applicable law requires them. If a seller refuses, you may need to decide whether to accept the home as-is, negotiate other terms, or walk away from the deal. Always review your contract and contingency rights carefully.
What deadlines should I be aware of when negotiating repairs before closing?
Inspection periods typically run seven to 15 days after the offer is accepted, with repair requests due within that timeframe. Sellers usually have three to 10 days to respond. These deadlines vary by contract and local practice, so review your purchase agreement closely to ensure timely negotiation and resolution before closing.
How we researched this
This article was assembled from 18 cited references.
Nothing here is based on hands-on testing. Where a figure or finding appears, it belongs to the source cited beside it, and the writing says so rather than implying otherwise. Every source is listed below so you can check it.
Sources
- How to Negotiate After a Home Inspection | Chase
- How to Negotiate After an Inspection
- How to negotiate after a home inspection: repairs, price or credit · BuyWise Home
- Negotiate Repairs After Home Inspection, Strategic Guide, BuyersCentral.com
- How to Negotiate Home Price: From Offer to Closing - LegalClarity
- How Much Do Home Inspection Repairs Cost? (2026 Guide)
- How Much Do Home Inspection Repairs Cost? (For Buyers, Sellers & Agents) | Upkeep Property Maintenance
- Repair Credits vs. Seller Repairs After a Home Inspection | PropWise
- Repair Credit vs. Seller Repairs: Which Should You Ask For?, Home Inspection Decoded
- Seller credit for repairs: how it works at closing · Kept
- What to Request When Negotiating Home Repairs in 2026 | Opendoor
- How to Handle Repairs and Credits During the Closing Negotiation | The Simple Lawyer
- How to Negotiate Repairs After a Home Inspection | Home Stimulus
- 7 Scary Signs Your Home Could Need Expensive Repairs
- An inspection report is not a repair list | DIY Home Inspections
- Negotiating Repairs After Home Inspection: A Buyer’s Plan | Alert Home Inspections
- Can a seller refuse buyer repair requests after inspection?
- What to Request When Negotiating Home Repairs in 2026 | Opendoor
Related Articles
Negotiating Home Repair Requests During the Selling Process
Learn how to negotiate home repair requests effectively and control costs during the selling process with practical tips and repair budgeting advice.
How to Negotiate Home Price: Effective Strategies Explained
Learn how to negotiate home price using market data, seller credits, and buyer limits to get the best deal on your home purchase.
Home Repairs Before Selling: Prioritize and Budget Smartly
Learn how to prioritize and budget home repairs before selling to attract buyers and avoid costly concessions.
Inspection Contingency in Competitive Home Buying
Learn how inspection contingencies affect your offer and financial risk when buying a home in a competitive market.